Column
Can You Apply for Japanese Permanent Residence While Doing Side Work? Work Status, Outside-Status Permission, and Tax Issues 【2026 Update】
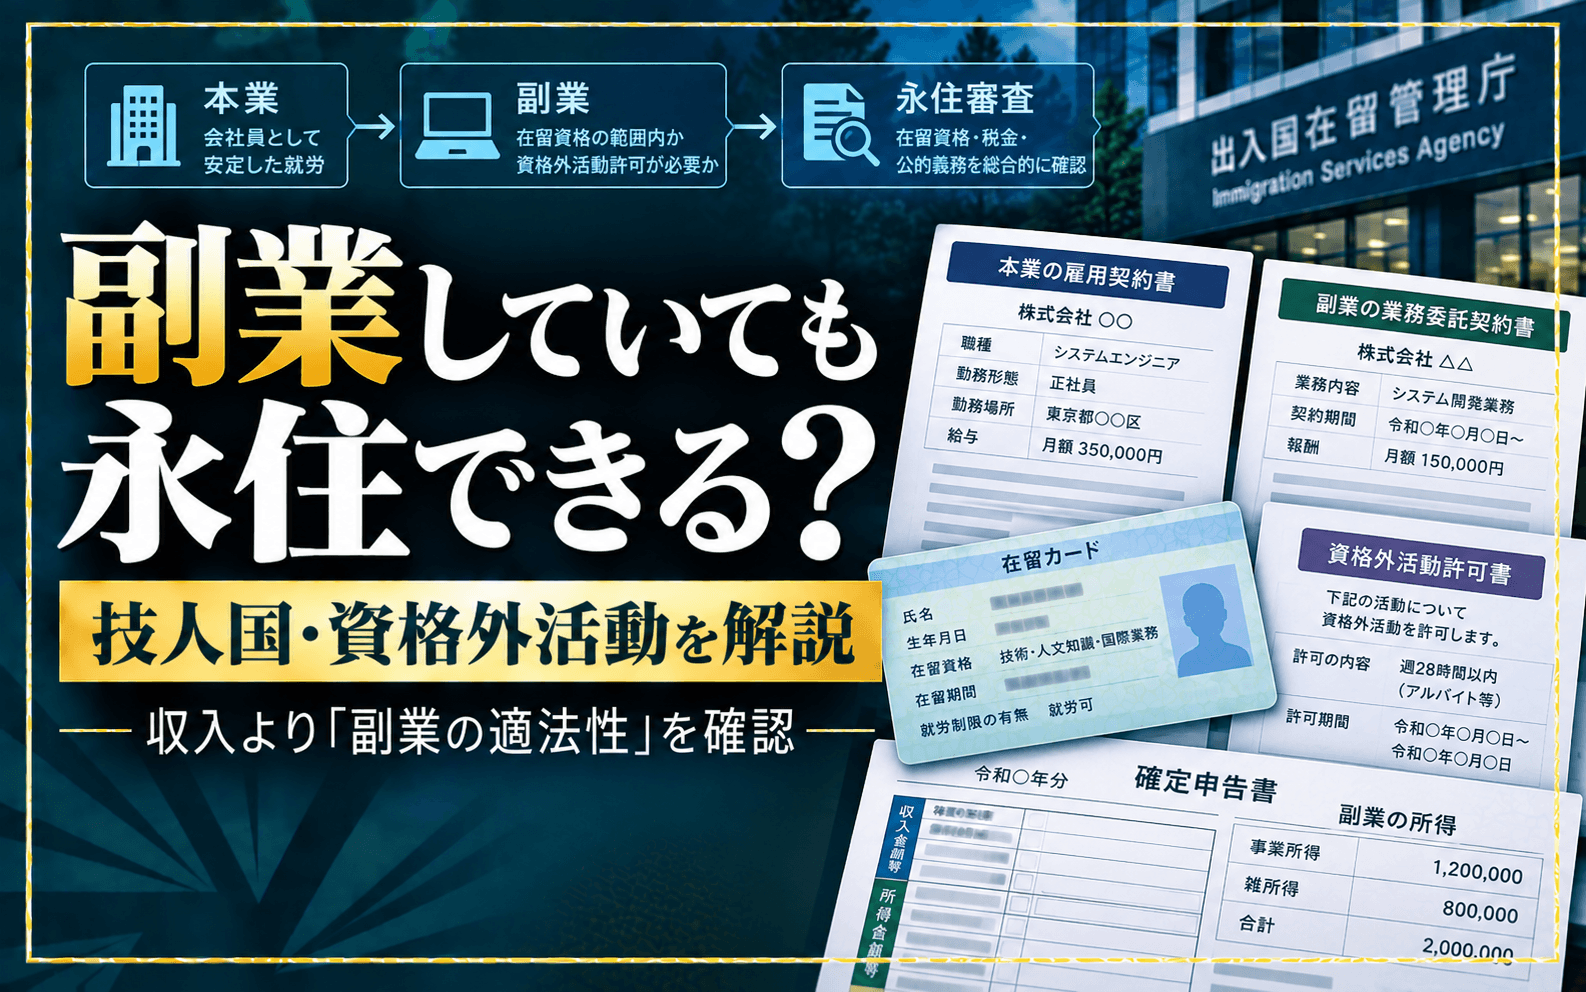
“I work full time but also have a side job.”
“I hold Engineer/Specialist in Humanities/International Services and receive freelance income.”
“I never obtained outside-status permission for my side work.”
The key point is:
side work does not automatically prevent Permanent Residence.
What matters first is whether the activity itself is lawful under the applicant’s immigration status.
Having a Side Job Is Not an Automatic PR Refusal Ground
The Permanent Residence guidelines do not prohibit side work itself.
However, the current guidelines require applicants to continue satisfying the criteria applicable to their present status of residence.
Accordingly, a case can present a problem where:
the principal employment is compliant,
but
the side activity is not.
A Work Status Does Not Permit Every Type of Side Job
Engineer/Specialist in Humanities/International Services authorizes particular professional activities based on contracts with public or private organizations in Japan.
It does not grant unrestricted permission to perform any paid work.
1. Similar Professional Work for Another Company
For example:
Main job: software engineer
Side work: software development for another company.
The side activity may fall within the same authorized professional category, depending on the actual duties and contractual relationship.
Changes or additions involving contractual organizations may also create immigration notification obligations.
The “28 Hours per Week” Rule Is Not a General Rule for Work-Visa Holders
The well-known 28-hour rule commonly applies to comprehensive outside-status permission used by Students and Dependents.
A person holding an ordinary work status does not automatically gain the right to perform unrelated side work for up to 28 hours per week.
For activity outside the authorized status, the actual proposed work needs to be reviewed and individual permission may be required.
Paid Activity Outside the Current Status May Require Prior Permission
Where an applicant plans to operate an income-generating activity or receive remuneration for activity outside the current status, Permission to Engage in Activity Other Than That Permitted may be relevant.
The issue should be addressed while the activity is being performed—not only when preparing the PR application.
A Freelance or Contractor Agreement Does Not Automatically Avoid Immigration Restrictions
Side work may be structured as:
Employment
Freelance work
Independent contracting
Service agreements
Immigration law looks at the substance of the actual activity rather than only the title of the contract.
“Freelance” therefore does not automatically mean the work is outside immigration restrictions.
Operating Your Own Business Requires Particular Care
A person may describe activity as a “side job” while actually:
Running an online store
Operating a consulting business
Establishing a company
Running a shop
Continuously acquiring clients and managing a business
At some point, the actual activity may be closer to operating an income-generating business than ordinary incidental side work.
That can require a broader review of the current status of residence.
What If Side Income Exceeds Main-Job Income?
For example:
Main salary: ¥4.5 million
Side income: ¥6 million.
The amount itself is not automatically prohibited.
However, it may become important to ask whether the applicant’s actual principal activity still corresponds to the status of residence they hold.
More Side Income Does Not Automatically Strengthen a PR Application
Stable income is relevant to Permanent Residence.
But side income should first be:
Lawful under immigration rules
Properly declared for tax purposes
Consistent with the applicant’s actual activities
An immigration-compliance problem cannot be solved simply by showing a higher total annual income.
Tax Compliance for Side Income Also Matters
Permanent Residence requires proper fulfillment of public obligations.
Depending on the nature and amount of the side income, income-tax filing and resident-tax treatment may become relevant.
An applicant should not treat:
“I do not want my employer to know about the side job”
as a reason to disregard tax obligations.
Employment rules and tax obligations are separate issues.
Previously Undeclared Side Income Requires Careful Review
Consider a person who earned side income for several years but did not complete tax filings that were required.
Ordinary work-status PR applications generally involve review of five years of resident-tax records.
The current PR guidelines also state that late fulfillment of public obligations can be evaluated negatively even where everything has been paid by the date of filing.
Accordingly:
correcting the tax position immediately before PR does not automatically eliminate the issue.
Filing Taxes Does Not Automatically Make the Side Activity Immigration-Compliant
Tax law and immigration law are different systems.
Paying tax on side income does not by itself prove that the activity was authorized under the applicant’s status of residence.
Likewise, an immigration-compliant side activity can still create a separate issue if the related tax obligations were not handled properly.
A New Side-Work Contract Can Also Create Notification Issues
Certain work-status holders must notify Immigration of prescribed changes involving contractual or affiliated organizations.
Accordingly, keeping the same main employer does not necessarily mean that no immigration notification could ever be relevant.
The PR guidelines expressly include immigration-law notification duties among public obligations.
What About Unauthorized Side Work in the Past?
Where the activity has already stopped, it should not automatically be assumed that the past conduct is irrelevant.
Relevant facts include:
When it occurred
How long it continued
Nature of the work
Income
Whether outside-status permission existed
Tax treatment
PR also considers the applicant’s overall compliance history.
YouTube, Social Media, and Online Sales Can Also Require Review
Modern side-income sources include:
YouTube advertising
TikTok and social-media income
Affiliate revenue
Online sales
Online teaching
Contracts with overseas companies
“Online income” is not automatically outside Japanese immigration rules.
The actual activity and whether it is occasional or ongoing matter.
Payment From an Overseas Company Is Not Automatically Irrelevant
Where an applicant lives in Japan and continuously performs paid work from Japan for an overseas company, the fact that the payer is located abroad does not necessarily answer the immigration-status question.
Highly Skilled Applicants Should Not Automatically Add Side Income to Their Point-Based Salary
The “annual remuneration” used in Highly Skilled Professional points and total taxable income are not necessarily identical concepts.
An applicant who calculates:
75 points from the main employment
plus side income
equals 80 points
should have the point calculation reviewed carefully.
Cases That Particularly Deserve Pre-Filing Review
Professional review can be useful where the applicant:
Holds Engineer/Specialist in Humanities/International Services and has a side job
Performs side work different from the main professional duties
Is unsure whether outside-status permission was obtained
Receives freelance or contractor income
Operates a side business
Earns more from the side activity than the main job
Receives ongoing YouTube, social-media, or e-commerce income
Receives compensation from an overseas company
Previously failed to report side income for tax purposes
Has a large mismatch between employment records and tax certificates
Uses side income in an HSP point calculation
Has not reviewed immigration notifications relating to additional contracts
Frequently Asked Questions
Q. Can an Employee With a Side Job Apply for PR?
Yes, potentially. The side activity and tax treatment need to be reviewed.
Q. I Have an Engineer Status and Do IT Work for Another Company.
The actual duties, contractual relationship, and applicable immigration notifications should be checked.
Q. I Only Work Five Hours per Week on the Side.
A short number of hours does not by itself establish that the activity is permitted.
Q. I Am Paid as an Independent Contractor. Does That Mean No Permission Is Needed?
Not necessarily. The substance of the activity matters.
Q. I Pay Tax on the Side Income.
Tax compliance and immigration authorization are separate questions.
Q. I Previously Failed to Declare Side Income.
The actual filing obligation, correction, payment timing, and relevant PR review period should be examined.
Q. I Receive Money From a Chinese Company.
The activity actually performed from Japan still needs to be reviewed.
Q. Side Income Brings My HSP Score to 80 Points.
Taxable side income cannot automatically be assumed to qualify as remuneration for HSP point purposes.
In a Side-Work PR Case, Check Legality Before Income
Side work may increase total income, but a strong PR application requires more than a high number on an income statement.
The central issues are:
immigration compliance + tax compliance + consistency of the submitted records.
Enlight Administrative Scrivener’s Office reviews the applicant’s main work, side activity, outside-status permission, contractual-organization notifications, tax records, resident tax, previous side activities, and HSP points before determining whether the PR application should proceed.
The initial Permanent Residence eligibility check is free of charge.
Permanent Residence support is generally limited to applicants within the jurisdiction of the Tokyo Regional Immigration Services Bureau.
References
Immigration Services Agency: Guidelines for Permission for Permanent Residence, revised February 24, 2026
Immigration Services Agency: Engineer/Specialist in Humanities/International Services
Immigration Services Agency: Permission to Engage in Activity Other Than That Permitted
Immigration Services Agency: Application for Permission to Engage in Activity Other Than That Permitted
Immigration Services Agency: Notification Concerning Contracting Organizations
Immigration Services Agency: Permanent Residence Application 3
National Tax Agency: Persons Required to File an Income Tax Return